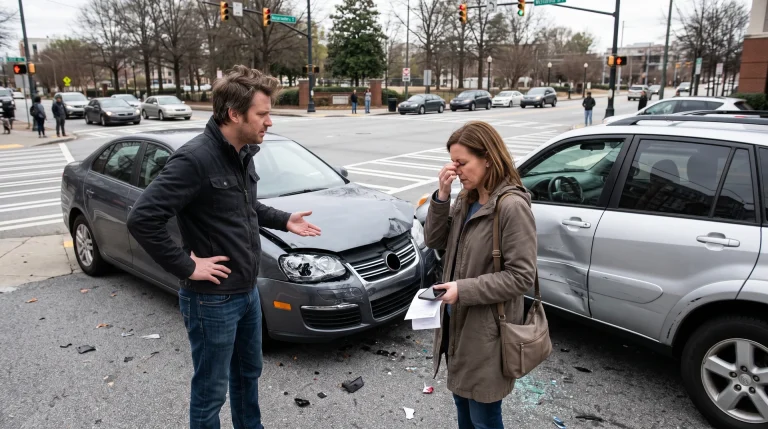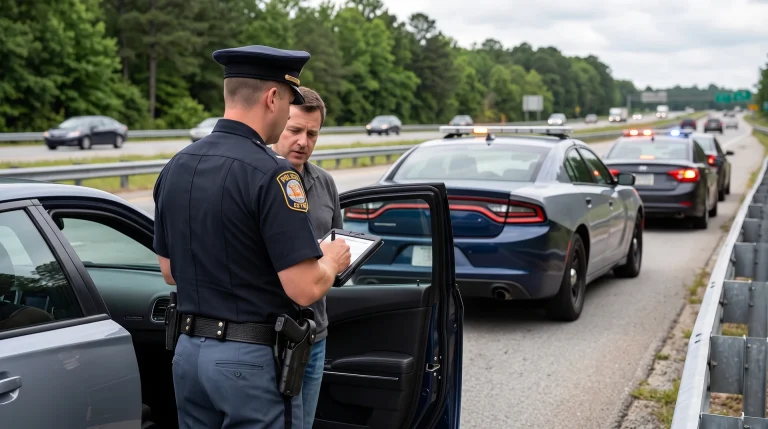
Uninsured motorist coverage, often called UM, can provide an important source of recovery when a legally responsible driver lacks applicable insurance or available liability coverage is insufficient. It is not a promise to pay every expense. Review the actual policy, insured status, type of coverage and proof of the loss.
Uninsured and Underinsured Losses
Georgia addresses uninsured and underinsured situations within O.C.G.A. § 33-7-11. A UM claim involves your own applicable coverage and legal requirements, rather than simply replacing every dollar an at-fault driver cannot pay. Responsibility, causation and damages still need support.
Coverage Depends on the Policy, Not a National Percentage
An undated statement that one in eight drivers is uninsured cannot determine whether your claim is covered. National estimates also should not be presented as a current Georgia rate. Obtain declarations, endorsements and any UM selection or rejection documents for the policy in force on the accident date.
What Losses May Be Addressed
Depending on the applicable provisions, UM can concern bodily injury and property losses within the statutory and policy framework. It differs from liability coverage, collision coverage and medical payments. The Georgia insurance commissioner’s auto guide explains those broad distinctions. Limits, deductibles, exclusions and the extent of proven damages still matter.
Georgia Coverage and Written Rejection
Georgia law generally requires UM provisions in covered motor policies unless a named insured rejects coverage in writing, with statutory rules and exceptions. UM should not be described as mandatory coverage that every driver necessarily has. A liability insurance card alone does not establish the amount or form of UM protection.
Unknown Drivers and Hit-and-Run Claims
The statute can treat an unknown owner or operator as uninsured. Unknown-motorist recovery generally involves physical contact unless the claimant’s account is corroborated by an eyewitness other than the claimant, along with reporting and other conditions. Do not assume a personal account alone always satisfies the requirements, or that property damage is categorically excluded.
Your Own Insurer Still Reviews the Claim
An insurer can investigate liability, policy applicability and the amount claimed. UM does not automatically guarantee faster handling, agreement or a fair settlement. Give accurate information, preserve correspondence and review cooperation duties, statement requests and releases in the actual policy context.
Identify Who Is Insured
The named insured, household members, occupants and users may raise different insured-status questions under the statute and contract. Do not promise that every passenger or family member is covered in every vehicle and circumstance. Ask which policies may apply and whether any exclusion or priority issue needs review.
Compare Coverage Before a Loss
Discuss available limits, premium, deductibles and exclusions with a licensed insurance professional. Cost depends on the applicant, insurer and selections; it is not always a universally small charge. Buying or increasing coverage after an accident does not cover a loss that has already occurred.
Added-On, Reduced-By and Other Policy Limits
Added-on coverage generally supplements available at-fault liability coverage up to applicable UM limits and proven losses. A reduced-by selection generally takes available liability coverage into account in determining the UM amount. The statute, written selections and actual available coverage control; the policy’s headline limit is not an automatic payment.
Multiple policies, offsets, prior payments and reimbursement obligations can complicate the analysis. Do not add every listed limit together or assume duplicate recovery for the same loss.
Review Disputes and Preserve the Required Evidence
Keep the police incident information, witness details, original photographs, medical and earnings records, policies and claim correspondence. Obtain advice about notice, lawsuit and service requirements promptly; an open claim does not automatically preserve every deadline.
Castan, Lecca & Boeschen can review applicable coverage and a disputed claim. Representation can help assess evidence and options without guaranteeing coverage, maximum compensation or a particular resolution.